Build a Monthly Budget with the Empowered Toolkit
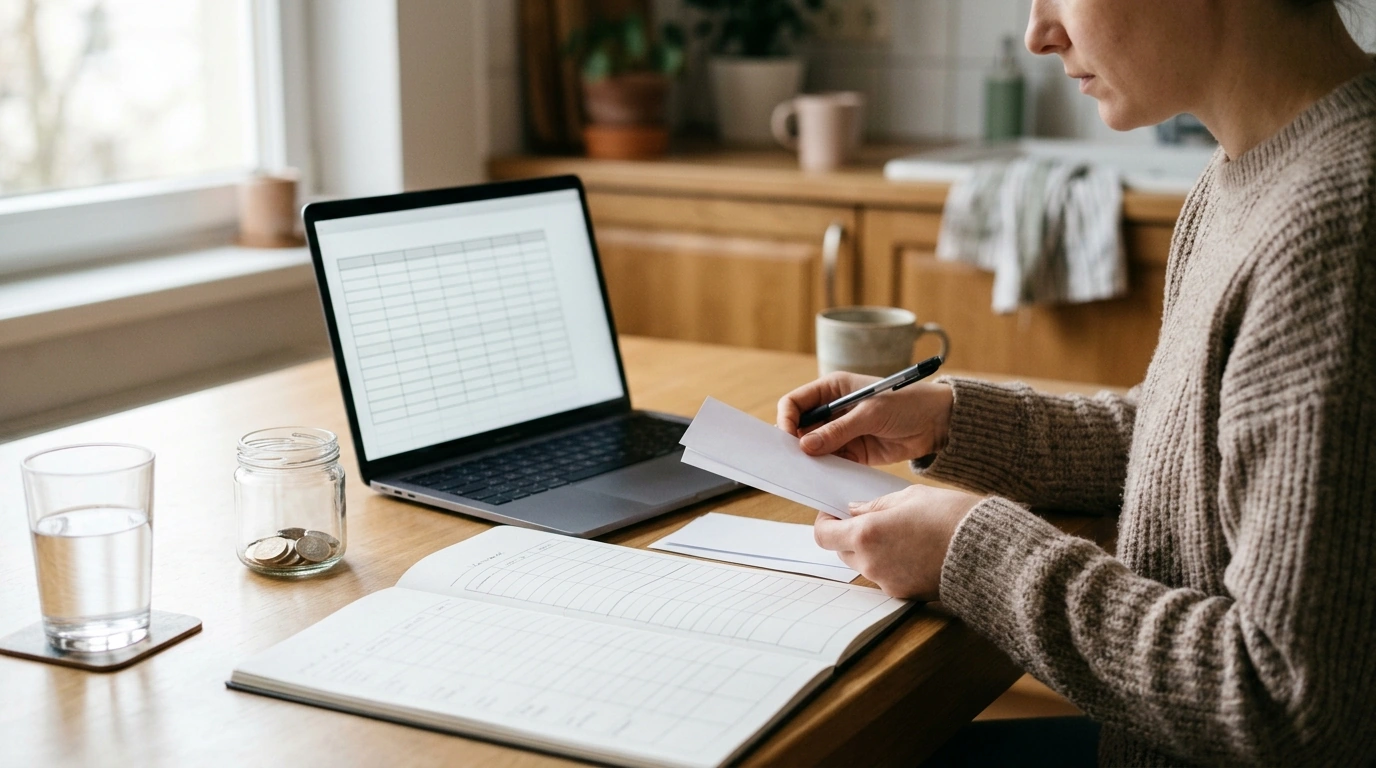
A monthly money routine doesn’t have to be complicated. A little time spent planning, checking in, and adjusting can help you see where your money is going and make more intentional decisions about what comes next. For more guidance, see OECD Journal on Budgeting, Volume 2023 Issue 1.
Our 4-in-1 bundle, The Empowered Budgeting Toolkit, brings together budget planning, savings strategies, and guided affirmations in one place. You can use its practical and mindset-focused resources to build a routine that fits your circumstances, without expecting any tool to guarantee a particular financial result. For further reading, see Explore NDI’s Free Financial Wellness Tools!.
What the Toolkit Brings Together
The Empowered Budgeting Toolkit includes a budget planner, an Excel guide, wealth strategies, and guided affirmations. The bundle is listed at $111.99.
Each part has a different role. The planner and guide can help you organize financial information, while the strategies offer ideas to consider as you make decisions. Affirmations can provide encouragement as you practice new habits, but they do not create wealth on their own or replace a financial plan.
Our team recommends starting with one manageable task rather than trying to overhaul everything at once. Even a simple list of income and expenses can give you a useful starting point.
Start with a Clear Monthly Picture
Begin by listing the take-home income you expect to receive during the month. If your income varies, you might use a conservative estimate and update it as payments arrive. Next, write down recurring bills, such as rent, utilities, insurance, and debt payments.
Add variable expenses, including groceries, transportation, and other purchases that may change from month to month. Look back at recent statements or receipts if you’re unsure what to include. It can also help to set aside room for occasional costs, such as annual fees or car maintenance, so they are less likely to catch you off guard.
Once you have a picture of what is coming in and going out, set spending limits that reflect your priorities. Use the planner and Excel guide to support a consistent record of your expenses in a way that works for you. The Consumer Financial Protection Bureau’s budgeting resources can also help you think through the basics.
A Simple Monthly Budget Check-In
| Step | Action | Purpose |
|---|---|---|
| Income | Record expected take-home pay | Establish money available to plan |
| Expenses | List fixed and variable costs | See where money is going |
| Savings | Choose an affordable contribution | Make progress toward a goal |
| Review | Compare the plan with actual spending | Adjust the next month’s plan |
A brief weekly check-in can help you update your records while purchases are still fresh in your mind. At the end of the month, compare your plan with what actually happened and note any changes you want to make.
Turn Savings Goals into Manageable Steps
Choose one specific goal to begin with, such as building an emergency cushion. Then decide on a monthly contribution that fits alongside essential expenses and required payments. A modest amount can be easier to maintain than an ambitious target that leaves no room for everyday needs.
Review discretionary spending for possible adjustments. You might decide to use a subscription less often, plan a few meals at home, or pause a purchase while you consider whether it matters to you. Protecting essentials comes first; savings decisions should reflect your actual circumstances rather than a rigid rule.
The toolkit’s wealth strategies can serve as prompts for informed planning, not promises of returns or individualized financial advice. For more ideas about preparing for unexpected expenses, explore the FDIC’s guidance on saving. If you need advice tailored to a complex situation, consider speaking with a qualified financial professional.
Make Room for a Supportive Money Mindset
Money decisions can bring up stress or frustration, especially when a month doesn’t go as planned. Guided affirmations may help you pause and return to the habits you want to practice. They work best as a complement to concrete actions, such as recording expenses and reviewing your savings goal.
Try a grounded statement: “I can take small, consistent steps toward my financial goals.” You might repeat it before your weekly check-in, then choose one practical action to take. The affirmation is a reminder of your intention; the action is what moves your plan forward.
If you enjoy an audio format, our Daily Affirmations for Abundant Wealth audio course is an optional companion to your budgeting routine.
Create a Routine You Can Return To
At the start of each month, plan around expected income, essential expenses, and an affordable savings contribution. Check your spending briefly each week, then use your month-end review to decide what needs adjusting. You can keep notes on what worked as well as what felt difficult.
Income and expenses change, and a missed target is information—not failure. Adapt the routine when you need to, and return to the next useful step. When you’re ready to explore the bundle, visit The Empowered Budgeting Toolkit.
FAQ
Who is The Empowered Budgeting Toolkit for?
It is an option for people seeking a structured approach to monthly budgeting, savings, and money mindset. Whether it fits your needs depends on your circumstances and preferences.
Do affirmations replace a budget or financial plan?
No. Affirmations may support motivation, but tracking income, expenses, and savings provides the practical foundation for a budget.
How often should I review my budget?
A short weekly check-in and a more complete monthly review are a useful starting point. Adjust the frequency to suit your needs and financial circumstances.


Leave a comment